Key Takeaway
Business interruption insurance after a fire replaces the net income your business loses while a covered fire forces you to close, but only if your policy includes the coverage and direct physical damage is documented. It typically covers lost profits, payroll, rent, taxes, and certain ongoing expenses during the restoration period. Coverage usually starts after a 48 to 72 hour waiting period and can extend up to 12 months depending on your policy endorsements.
If you own a business, a building, or rent to tenants and you’re standing outside a fire-damaged property, here’s the direct answer: business interruption insurance may replace the income you lose while your business is closed, but only if your policy includes the coverage and a covered fire caused direct physical damage that forced operations to stop or slow down. This coverage is also called business income insurance. It works alongside your property insurance policy, which pays to repair or rebuild the building. Property insurance fixes the structure. Business interruption insurance covers the money you lose while it’s out of service. The coverage isn’t sold on its own; it rides along with a commercial property policy, a business owner’s policy (BOP), or a stand-alone endorsement. Most small business owners never read this part of their insurance policies until a fire forces them to.
First, make the property safe and preserve your claim record

The fire already made this urgent. What you do in the first day protects both your safety and your insurance claim. The U.S. Fire Administration (part of FEMA) recommends a clear sequence.
- Confirm it’s safe to enter. Check with the fire department before going back in.
- Contact your insurance provider promptly. Report the loss and ask what to do to keep the property safe until it’s repaired.
- Ask before you clean up. Find out who to talk to about cleanup and what you can move or remove.
- Document before discarding. Photograph the property damage, including broken windows and structural harm. Don’t throw anything out until your insurer has guided you.
- Save every receipt tied to the fire loss, including temporary repairs and extra costs.
Clear records are what connect your financial loss to the covered physical damage. That connection is the backbone of a business interruption claim.
Business interruption insurance vs. commercial property insurance
These are two different coverages that solve two different problems. Commercial property insurance pays to repair or replace the physical damage: the structure, equipment, inventory. Business interruption (business income) coverage replaces the net income you lose while you can’t operate, plus certain continuing and extra expenses.
They work together. According to the National Association of Insurance Commissioners (NAIC), business interruption coverage is usually tied to commercial property coverage and pays for lost net income during the closure while repairs are underway. Treat business interruption as a separate component of your overall property claim, documented and calculated on its own terms. The property damage side and the lost income side each need their own proof. Business interruption insurance compensates for the earnings the physical location would have produced had the fire never happened.
The four-part test for business insurance after a fire

Before anything else, work through four questions. Regulators like NAIC and the California Department of Insurance (CDI) describe when coverage applies this way.
- Do you have business interruption / business income coverage? It isn’t automatic in every business insurance policy.
- Is fire a covered peril on your policy? Fire insurance is a standard covered cause of loss on most commercial forms.
- Was there direct physical loss or damage? Coverage generally requires direct physical property loss from a covered peril.
- Did that damage cause a necessary suspension or slowdown of business operations? The interruption has to be tied to the covered loss.
Check your declarations page and any endorsements, or ask your insurance provider, broker, or agent. Coverage, exclusions, limits, and deductibles vary from one policy to the next, and no two businesses affected by a fire have identical insurance coverage.
What business income coverage includes after a fire
The answer depends on your specific policy, but the Insurance Information Institute and NAIC describe items that a business interruption insurance policy commonly helps with during the restoration period:
- Lost net income, or profits, the business would have earned
- Rent, lease, or mortgage payments
- Loan payments
- Employee wages and payroll
- Taxes
- Certain ongoing expenses that don’t stop just because the doors are closed
Every item here is policy-dependent. And the lost income is calculated from your own financial records, not from a guess. That’s why the paperwork matters so much: your books define what gets paid on a covered loss. As one example, if a small business normally earns steady monthly income and a fire shuts it down for weeks, business interruption insurance helps stand in for the business income those weeks would have produced, once the loss is documented. Business interruption insurance typically pays only for what your records can support, and business interruption coverage typically ends when repairs are complete.
What is extra expense coverage and civil authority coverage?
Extra expense coverage reimburses the reasonable costs of keeping the business running during repairs. CDI describes these as costs like a temporary location or office space, equipment or vehicle rental, and advertising to let customers know you can still continue operating. If spending money now keeps revenue coming in, extra expense coverage is often what supports it.
Civil authority coverage may apply when a government order prohibits access to your business premises. NAIC notes the standard wording generally requires complete prohibition of access, physical damage to nearby property, and that the damage came from a covered peril. Triple-I says this coverage typically doesn’t exceed two consecutive weeks and is highly policy-specific. A wildfire evacuation order alone does not automatically trigger business interruption coverage; the nearby-physical-damage requirement still has to be met.
One more term to know: contingent business interruption coverage covers losses caused when a supplier or major customer suffers covered damage. That’s background, not the core of most fire claims.
What business interruption insurance usually does not cover
Being honest about the limits is part of getting the claim right. Business interruption insurance coverage generally will not pay for:
- Income you can’t document in your financial records
- Flood, earthquake, or mudslide losses from natural disasters without separate coverage
- Pandemic, virus, or communicable diseases losses
- Financial losses not tied to covered physical damage
Insurance companies review these claims closely, and Triple-I notes that undocumented income typically isn’t paid. That’s not a reason for worry. It’s a reason to keep good records so your covered loss is easy to verify.
How long does a business interruption policy pay after a fire?

Two policy terms control the timing. The waiting period is the gap before coverage kicks in; Triple-I says this is typically 48 to 72 hours. The period of restoration is how long the coverage pays while the insured property is being repaired.
Triple-I notes the standard property policy limits the restoration period to about 30 days, but it can be extended by endorsement, sometimes up to 360 days, and many insurers cover up to roughly 12 months of lost income. These are industry generalities, not promises. Your declarations and endorsements set the real numbers for your business, and other factors like your claims history can shape what an insurer offers.
There’s also extended business interruption, which NAIC defines as coverage for the stretch after the property is repaired but before your income climbs back to pre-loss levels. Reopening rarely means instant recovery, and that gap is what this interruption insurance addresses.
What business interruption insurance cost depends on
You won’t find one flat price for this coverage, and anyone quoting a firm number without knowing your business should give you pause. Business interruption insurance cost generally tracks your business income, your industry, how long you’d likely be closed after a loss, and the limits and endorsements you choose. Higher revenue and a longer expected restoration period tend to raise the premium. The honest answer for your business comes from your broker or insurance company reviewing your actual books, not from a rule of thumb.
How do you prove a business interruption claim after a fire?

A strong claim proves two things at once: the physical fire damage and the lost income tied to the shutdown. Triple-I advises building both sides of the file. Many businesses lose track of this paperwork in the chaos, so start early.
Financial proof:
- Tax returns and monthly sales-tax returns
- Profit-and-loss statements showing lost profits
- Business contracts and budgets
- Payroll records
- Receipts for extra and temporary-location costs
- Records of continuing expenses during the suspension
Property-damage proof:
- Date of loss and photos of the damage
- Mitigation logs and scope of damage
- Repair or reconstruction schedule
- Completion documentation
Report the claim promptly, and remember that income you can’t document generally won’t be paid. The cleaner your records, the faster your insurance company can confirm what a covered event forces them to pay.
How a licensed fire restoration and reconstruction company supports the claim
A restoration and reconstruction team protects the property side of your proof. That’s the lane we work in, and it’s genuinely useful when a covered event closes your business activities.
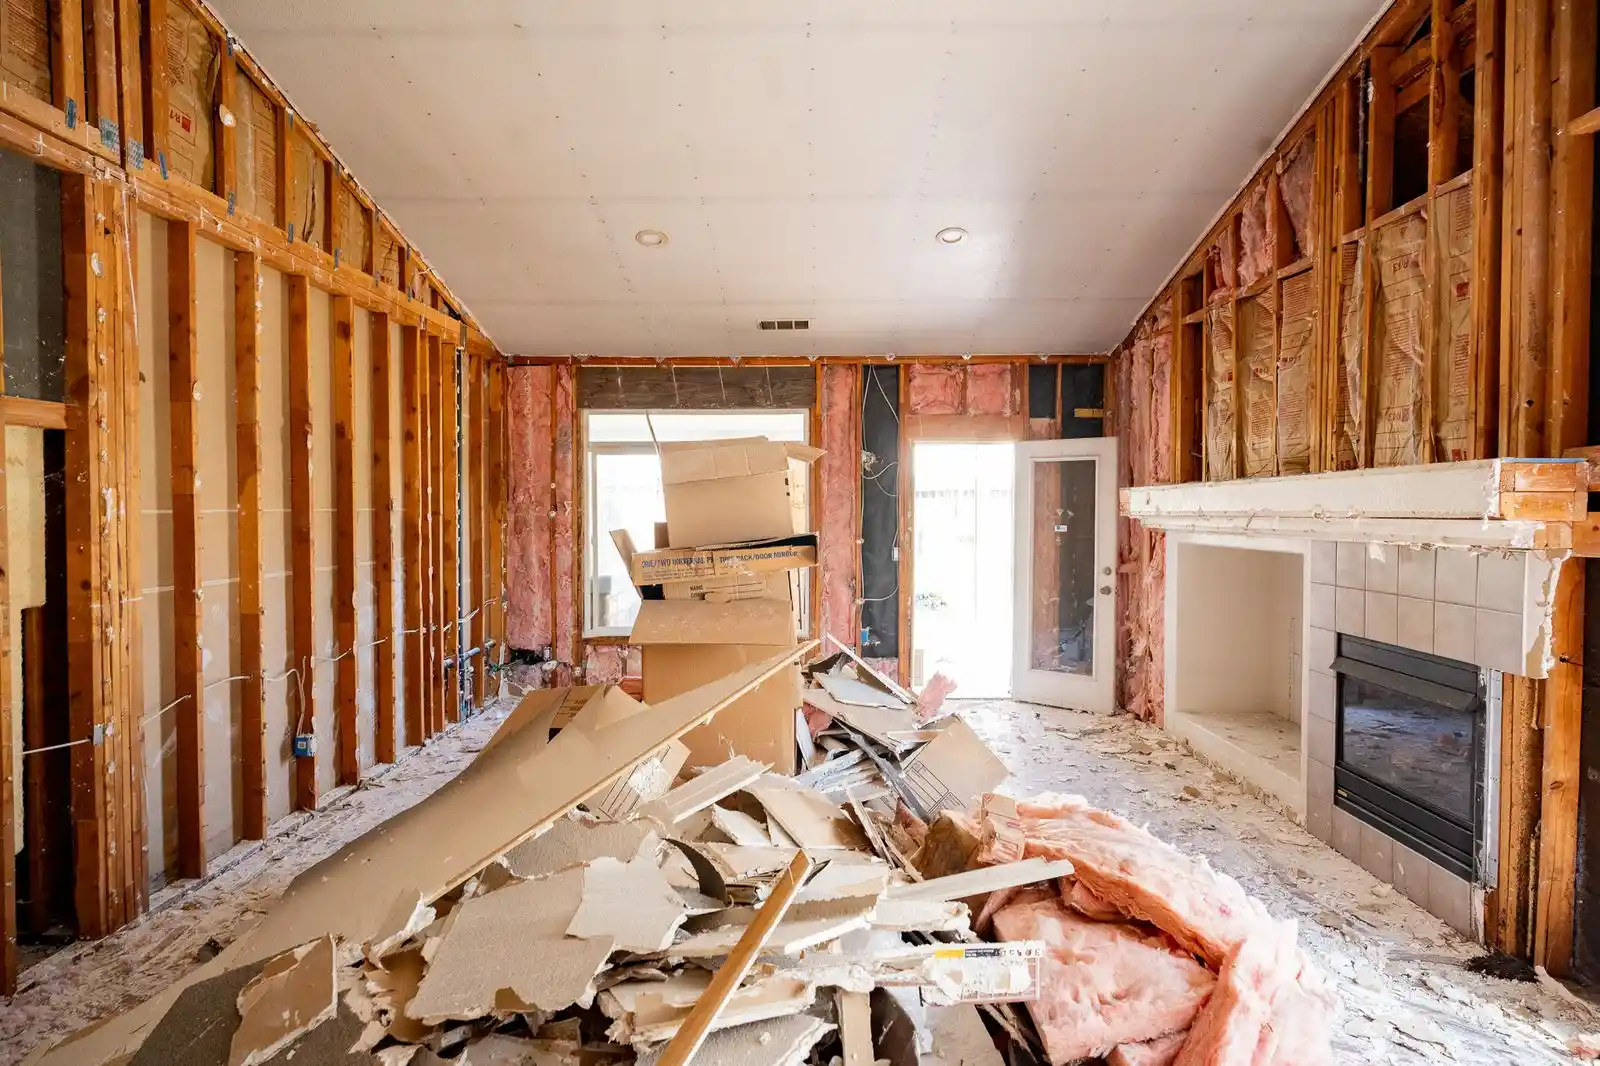
A licensed, IICRC-certified fire company documents the damage as it works: emergency board-up and roof tarping, smoke and soot assessment, drying of fire-suppression water (EPA advises drying affected areas within 24 to 48 hours to help prevent mold), contents documentation, and hazardous-material testing for asbestos or lead where warranted. It defines whether the job is a repair or a full rebuild, records milestones and QA inspections, and provides a signed certificate of completion. Those records help tie your repair costs and timeline to the covered loss. When a fire forces business owners to close temporarily, this documentation shows exactly why and for how long.
One line matters more than the rest: a contractor can document damage, scope, and timeline, but a contractor cannot decide insurance coverage. That call belongs to your insurer, broker, public adjuster, and accountant. Anyone who promises a coverage outcome is telling you something they can’t know.
California notes for Pasadena and Southern California business owners

If your loss is in California, a few state rules work in your favor. CDI requires insurance companies to acknowledge a notice of claim no more than 15 calendar days after receipt, and to accept or deny a claim no more than 40 days after receiving proof of claim, subject to exceptions. Those deadlines are guardrails you can hold your insurer to.
Public adjusters in California are licensed by CDI, so verify the license before hiring anyone. In a declared-disaster area, a public adjuster may not solicit business until 7 calendar days after the loss-producing event ends, and you can cancel a public-adjuster contract within 72 hours of signing. If your coverage runs through the California FAIR Plan, note its commercial fire policy is a named-peril form, so any business interruption element must be verified against the exact policy and any companion coverage. This may be offered as an add on rather than built in, and it covers losses related to a certain amount of documented income only. And if you’re also a homeowner rebuilding, CSLB caps disaster residential rebuild down payments at $1,000 or 10% of the contract, whichever is less.
Red flags to watch for after a fire
You’re a target for pressure right now, so know what protects you. Be cautious of anyone who quotes a firm price without seeing the property, pushes a “sign by Friday” deadline, won’t show proof of license or insurance, or demands an improper upfront payment. Walk away from anyone who tells you to discard evidence before your insurer weighs in, or who promises a specific coverage result. None of those behaviors serve you.
Frequently Asked Questions
Talk to a licensed, fire-focused restoration and reconstruction team

An honest scope for your property requires seeing it. Anyone quoting firm numbers sight-unseen is a red flag, not a shortcut. Golden Coast Construction & Restoration is a fire-focused company with permanent local offices and 24/7 emergency board-up, IICRC-certified crews, by-the-book milestone payments, and documentation built to support your insurance claim from inspection through a signed certificate of completion. For California work, verify our license (CSLB #838443) through the CSLB before you sign. When you’re ready, reach out for an on-site fire damage assessment. No pressure, no promises we can’t keep.