Key Takeaway
Detached garage fire damage is covered under most homeowners insurance policies as an Other Structures loss, typically capped at 10% of your dwelling limit. Stay out until officials clear access, document everything before cleanup, and have both the garage and the nearby home inspected. Restoration and rebuild are different scopes with different costs, and confusing them leads to the wrong estimate.
Treat a detached garage fire as a separate-structure loss. Stay out until the fire department or local officials say it’s safe, document everything before you clean up, call your insurance company, and have both the garage and the nearby home inspected. If you’re early in a claim and unsure what’s covered, here’s the short version: a detached garage usually falls under your policy’s Other Structures coverage, often limited to about 10% of your dwelling limit, and it’s covered separately from the house. One more distinction worth knowing now, because it shapes everything that follows: restoration (cleaning and drying) is not the same as rebuilding (reconstruction after major loss).
Don’t enter the garage until it’s cleared for access

The urge to rush in and save your tools is normal. Wait anyway. A garage that’s still standing can hide hot spots, weakened framing, a compromised roof, and live electrical hazards that aren’t visible from the driveway.
Garages also store the things that make fire worse: fuel, propane, paint, solvents, and batteries. Lithium-ion batteries can overheat and reignite hours after the flames are out. Let officials and fire investigators confirm access before anyone goes inside. Getting access to the structure too early is one of the most common ways homeowners get hurt after a fire.
Once it’s cleared, an open or damaged structure needs securing. Emergency board-up, roof tarping, or temporary fencing keeps out weather, animals, and people while you sort out the claim. Most policies expect you to protect the property from further damage while the claim is open, so securing access matters for coverage too. Downed limbs may also call for tree removal before a crew can work safely.
Is detached garage fire damage covered by homeowners insurance?
Usually, yes. A detached garage typically falls under Coverage B, Other Structures, which is normally capped at 10% of your dwelling (Coverage A) limit. Your specific homeowners policy controls the number, so this is a starting point, not a guarantee. Whether you have sufficient coverage depends on what it would actually cost to rebuild.
The difference matters: an attached garage is generally part of your dwelling coverage (Coverage A), while a detached one sits in Coverage B with its own coverage limit. Fire and smoke are typically covered perils. Common exclusions include flood, earthquake, and damage from wear, tear, or neglect. Understand that these limits are set by the policy, not the contractor.
Pull your declarations page and read the Coverage B limit. Total destruction of a garage is possible, and that 10% figure can run short when it does. If it looks low for your property, ask your insurance agent to review it and increase it for next time. A quick call to your agent before you file can also tell you what your policy actually says about detached other structures.
What about the personal property, belongings, and cars inside?

Contents like tools, stored belongings, and hobby gear usually fall under personal property coverage. Some categories carry sub-limits, though, including firearms, collectibles, and other valuable items, so review your policy before you assume a full payout. For example, a small business inventory kept in the garage may be capped well below its real value.
Here’s the protective habit that matters most: don’t throw anything away before you photograph it and ask your adjuster. Damaged personal property is still evidence for your claim.
A burned car is a different claim. That goes through your auto comprehensive coverage, not your homeowners policy, so call your auto insurance company separately about any cars affected. And a car parked near the garage, not inside it, can still be heat-damaged. Document those too, because the insured value only gets paid if the loss is recorded.
A detached fire can still reach your house, pets, and neighbors
The word “detached” describes your insurance, not physics. Radiant heat can warp siding, crack windows, melt gutters, and scorch fences and roof edges on the nearby home. If pets or neighbors are close by, account for them early in the event.
Smoke and soot travel further than most people expect. They move through open windows, vents, attic gaps, and HVAC intakes, and ash gets tracked indoors on shoes and clothing. Firefighting water can flow toward the house or into shared utility lines. This is why a good inspection can’t stop at the garage, and why both structures belong in the same claim review.
If the loss makes part of your home unlivable, ask your adjuster about additional living expenses coverage, which many policies include to help with temporary housing while repairs are underway. Sorting this out early protects your daily life during a hard stretch.
What a proper fire-loss inspection should include

A thorough inspection looks past the visible burn marks, because the real damage to the property is often worse than it appears. A complete review covers:
- Structural framing, roof, walls, and slab or foundation
- Garage door, opener, tracks, and support framing
- Electrical panel, subpanel, wiring, outlets, and any EV charger
- Gas and water lines, appliances, and HVAC or mini-split units
- Smoke and soot residue and odor boundaries
- Fire-suppression water and moisture mapping
- Mold-risk check (EPA advises drying within 24 to 48 hours; absorbent materials that stay wet may need removal)
- A contents inventory of personal property
- Asbestos and lead testing where warranted
- A separate look at the nearby home for exposure damage
Professional fire and smoke work follows a real standard, ANSI/IICRC S700-2025, which covers residue assessment, cleaning, and odor management. Knowing a standard exists helps you tell a specialist from a guess, and it helps you review any estimate against something real. This applies across different types of fire and smoke loss.
Restoration or rebuild? They’re not the same
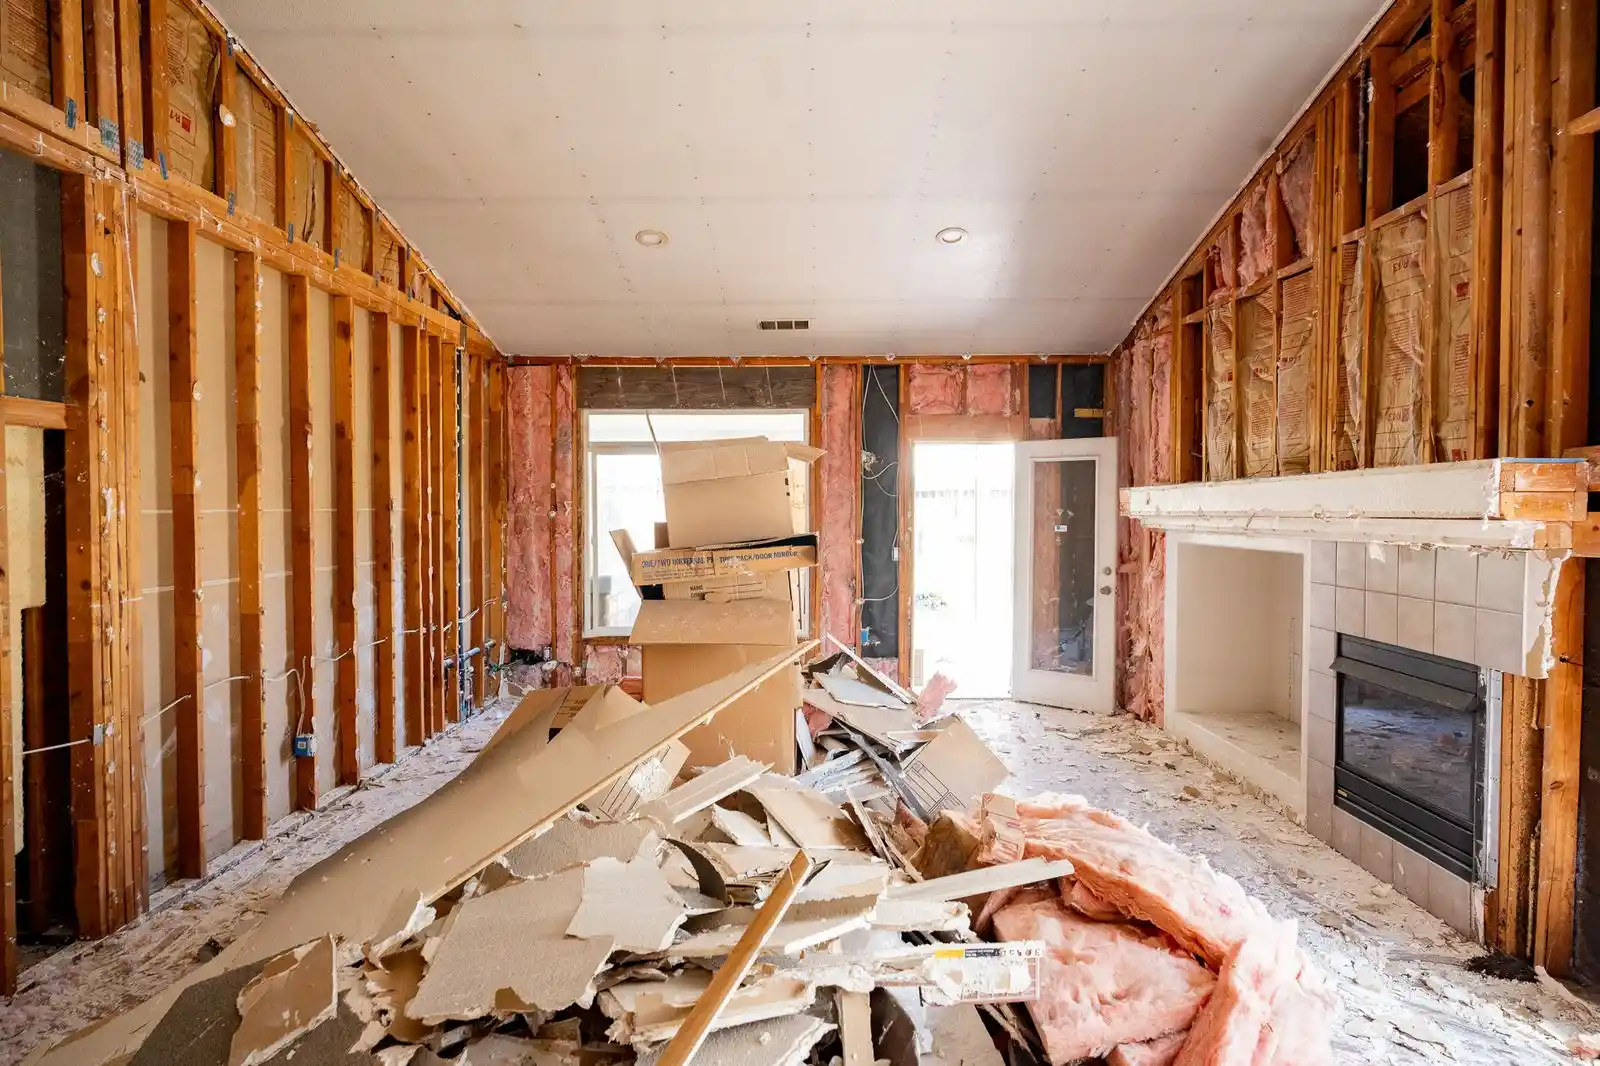
Restoration means cleaning, soot and odor removal, contents work, drying, and minor repairs. Reconstruction means demolition, plans, permits, framing, roofing, and a code-compliant rebuild after major or total loss of the structures involved. A full replacement of the garage is a different job than salvaging it, and confusing the two leads to the wrong scope and the wrong cost.
A garage can look like it’s standing and still need an engineer, an electrician, or a building official to sign off before anyone touches it. And no honest contractor can hand you a firm cost sight-unseen. A real figure needs an on-site inspection based on what a crew finds, and anyone quoting one without seeing your property is a red flag. That is an important question to ask before you sign.
California rules that protect you during the claim

California gives you specific protections. Use them.
- Verify the license. Check any contractor or restoration company through the CSLB; the license lookup is public.
- Down-payment cap. A home improvement down payment can be no more than 10% of the contract price or $1,000, whichever is less.
- Right to cancel. You generally have a 3-day right to cancel a home-improvement contract. A 5-day right applies for homeowners 65 and older; verify it before relying on it.
- Document the claim. The California Department of Insurance advises keeping a proof-of-loss record and a log of claim communications with your insurance company and adjuster.
For Pasadena rebuilds, the city’s permit and inspection process applies, and South Coast AQMD requires an asbestos survey before demolition or renovation regardless of the building’s age. That matters because EPA notes lead paint is considered more likely in homes built before 1978 and asbestos in buildings before 1970. If your contractor’s estimate lives on a shared portal or server, keep your own copies too; a link that starts with http today may not open a year from now.
Key takeaways before you sign anything
A detached garage is its own structure on your policy, but the fire doesn’t respect that line. Get both buildings inspected. Read your Coverage B limit and your deductible before you assume a number. In addition, keep every damaged item until your adjuster grants permission to dispose of it. And verify the license of anyone who asks to touch your property. Take the time to discuss the full scope with your adjuster so nothing is missed.
How Golden Coast Construction & Restoration can help
We handle fire recovery from 24/7 emergency board-up through full reconstruction, one contractor from emergency to move-in. We ensure the scope is documented and easy to follow. California work is licensed under CSLB #838443, which you can verify, and you should verify any contractor before signing. We’re IICRC-certified, with a permanent office serving Pasadena and Southern California. We work directly with insurance adjusters, document the scope, and tie payments to completed milestones. When you’re ready, we’ll come look at the garage and the house and give you an honest read in person.