Key Takeaway
Fire damage restoration cost in Washington varies widely because no two fires cause identical damage – scope is determined only after an on-site inspection of smoke travel, water intrusion, contents, hazardous materials, and permit requirements. A complete estimate separates restoration from reconstruction and accounts for HVAC, concealed spaces, and code upgrades. Anyone quoting a firm total without walking the property is guessing.
There is no honest statewide price for fire damage restoration in Washington. The same phrase covers everything from cleaning smoke residue out of one bedroom to rebuilding a house down to the framing, so a number that means anything comes from an on-site inspection: what burned, how far smoke traveled, what firefighting water soaked, what can be cleaned, and what has to be replaced. Anyone who gives you a firm price before walking the property is guessing.
This is written for a Washington homeowner a few days or a few weeks out from a fire, probably mid-claim, trying to tell a fair estimate from a bad one. Below: what actually drives the cost, what belongs in a written estimate, what your policy may pay, and what state law lets you verify before you sign anything.
Why Fire Damage Restoration Cost Can’t Be Quoted Per Square Foot
National cost guides publish per-square-foot charts and average totals that disagree wildly with each other. Most are built from proprietary models or contractor-reported figures, not from any Washington dataset, and none of them account for the one thing that sets your price: the documented scope of your loss.
Picture two houses on the same street, identical square footage, both with a kitchen fire. In the first, smoke pulled through the return duct and coated the inside of the HVAC system, and suppression water ran under engineered flooring into the subfloor. In the second, the fire was knocked down fast, doors were closed, and the damage stops at the kitchen ceiling. Same square footage. Two entirely different projects. Meanwhile, structural damage often hides in a small area while smoke spreads through the whole house, so square footage cuts in both directions at once.
One more myth worth clearing up: the class of fire does not set the price. A grease fire leaves oily, staining residue that behaves differently on painted drywall than a smoldering electrical fire’s fine, acidic soot does on metal and wiring. That changes cleaning methods and which materials are salvageable. It tells you nothing about how far the smoke went or whether the framing held. If someone quotes a total from photos or a phone call, treat that as a reason to keep looking.
Restoration vs. Rebuilding: Two Different Kinds of Cost
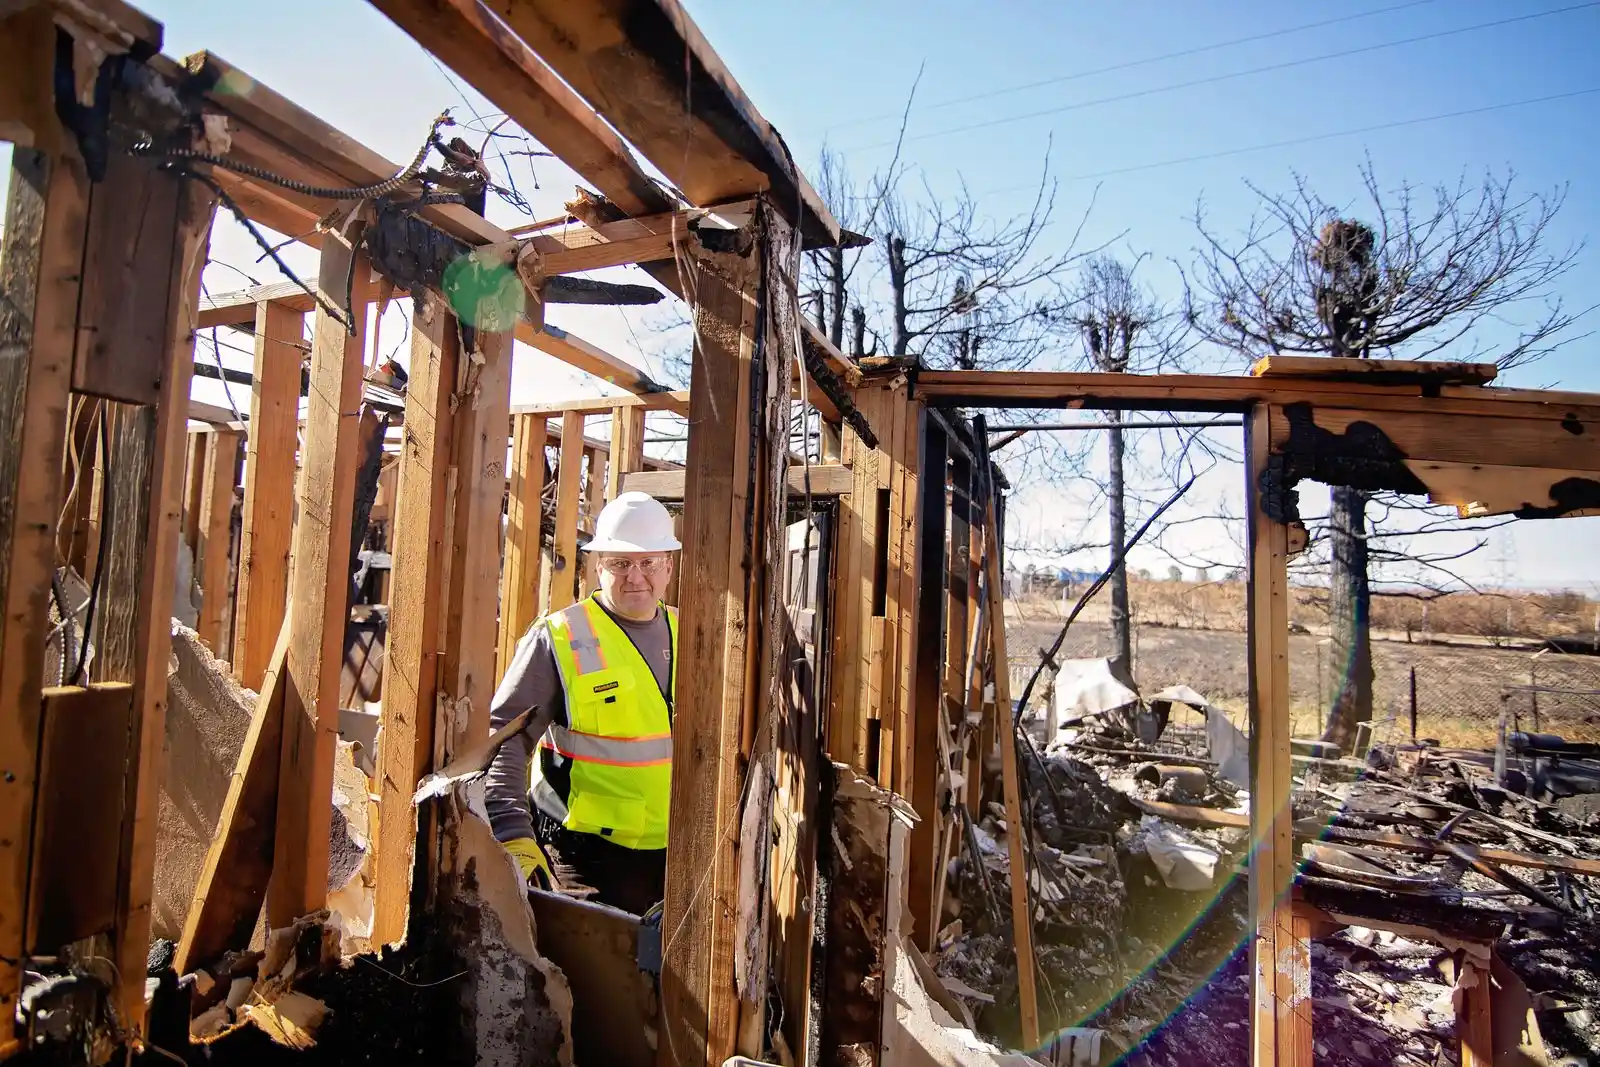
These two words get used interchangeably, and that confusion costs homeowners real money. Restoration means stabilizing the building, drying it out, removing soot, treating odor, saving what can be saved, and doing selective demolition and repair. Reconstruction means rebuilding: framing, roof, electrical, plumbing, mechanical systems, drywall, cabinets, finishes, or a substantial share of the house. Different trades, different timelines, different money.
The current fire and smoke standard, ANSI/IICRC S700, published in its first edition in 2025, covers assessment, mitigation, source removal, cleaning, odor management, HVAC, contents and documentation. It does not comprehensively address reconstruction, and its stated scope excludes wildfire, with IICRC beginning a revision in December 2025 to add wildfire content. So even the governing standard treats these as separate disciplines.
| Restoration | Reconstruction |
|---|---|
| Emergency board-up and stabilization | Structural framing repair or replacement |
| Drying after fire suppression | Roof and floor system rebuilding |
| Soot and smoke cleaning | Electrical, plumbing and mechanical replacement |
| Odor treatment and HVAC cleaning | Drywall, cabinets, flooring and finishes |
| Contents cleaning and storage | Major or total-loss rebuild |
| Selective demolition and repairs | Permits, engineering and inspections |
If a near-total loss gets scoped as a cleanup, the shortfall shows up months later as change orders and supplements. We cover the distinction in more depth in our separate article on fire restoration versus full reconstruction.
What Actually Determines Your Fire Damage Restoration Cost
An estimate is the sum of documented line items. Each factor below either adds scope or removes it, and every one of them has to be observed in person before it can be priced.
How much burned, and whether the structure is compromised
Flame damage is measured by what lost strength, not by how bad a room looks. Charring depth on framing, heat exposure to steel connectors, and deflection in roof or floor systems decide whether a member gets cleaned and sealed, sistered, or replaced. A small scorched area near a bearing wall can mean more work than a badly blackened but structurally sound room. Significant framing loss usually warrants an engineer’s evaluation.
How far smoke and soot traveled
Smoke moves with air. It pushes through wall cavities, ductwork, recessed lighting, and into closed cabinets and drawers well beyond the room that burned. Oily soot from cooking fires smears on porous surfaces; the fine residue from electrical fires settles differently and can corrode metal over time. Nonporous surfaces usually clean. Porous ones, like insulation and some textiles, often can’t be saved, and inspection is what tells you which is which.
Water used to put the fire out
Suppression water is part of fire recovery, and it has its own clock. EPA guidance says wet materials should be dried within 24 to 48 hours to reduce the likelihood of mold growth. Water runs downhill and sideways, into wall bases, under flooring, into crawl spaces. Moisture that is never measured or documented turns into secondary damage and a supplement request three weeks later, after the insurer has already written the first estimate.
What can be cleaned versus what has to be replaced
Material type drives the salvage decision. Sealed hardwood, tile, metal and solid-surface counters often clean well. Fiberglass insulation, wet drywall, particleboard cabinet boxes and many engineered floors do not. Salvage lowers your cost when it genuinely works. When a surface is cleaned, painted, and the odor comes back, you pay twice. That judgment call belongs in writing, room by room.
Contents: cleaning, pack-out and inventory
Furniture, clothing, electronics and personal belongings are usually a separate part of the claim from the building itself. Some items are cleaned on site, some need pack-out to a facility with ultrasonic or ozone-free deodorizing equipment, and some are non-salvageable and need to be inventoried for your personal property coverage. A written contents inventory with photographs protects you whether an item is cleaned or claimed.
HVAC systems and concealed spaces
Ducts, attics, crawl spaces and wall cavities are where scope gets missed. If the system ran while the house was smoky, residue is in the ductwork and will keep reintroducing odor after every visible surface is spotless. Attic insulation holds smoke particles. Opening and inspecting these areas early is cheaper than discovering them after new drywall is up.
Asbestos and lead-safe requirements
Washington L&I rules require suspect materials that will be disturbed during repair, renovation or demolition to be evaluated through a good-faith inspection by an accredited inspector, or handled as asbestos-containing material. This is not limited to old houses. Wall and ceiling texture, joint compound, flooring and adhesives, insulation, roofing and siding, and materials around stoves and furnaces can all contain asbestos. For homes built before 1978, federal and state lead-safe renovation rules apply to compensated work disturbing more than six square feet of paint per room indoors or twenty square feet outdoors. Emergency work to protect the property can receive limited exemptions, but cleanup and recordkeeping obligations may still apply once the emergency passes.
Permits, code compliance and engineering
Repairs have to meet current code, not the code the house was built to. Washington is operating under the 2021 State Building Code, effective March 15, 2024, with the 2024 cycle scheduled to take effect May 3, 2027. Renton requires permits for regulated construction, alteration, repair and demolition, with separate trade permits for electrical, plumbing, mechanical, and fire sprinkler or alarm work. Check with your own city or county building department, since requirements vary. Code-driven upgrades can widen the reconstruction scope, and whether your policy pays for them depends on ordinance or law coverage.
Access, scheduling and materials
A steep lot, a narrow street, or a home that has to be secured before anyone can safely enter all add labor. So does waiting on a discontinued cabinet line or a specialty window. These rarely dominate an estimate, but they belong in the schedule discussion up front.
What Belongs in a Written Fire Restoration Estimate

A total on one page is not an estimate. What you want is a scope you can compare against another contractor’s scope and against the insurance adjuster’s. Look for:
- Room-by-room measurements and a written scope for each area
- Photographs tied to the affected locations
- Emergency work listed separately (board-up, tarping, temporary power or fencing)
- Demolition and debris disposal, including what gets removed and why
- Drying with moisture readings and daily documentation
- Cleaning methods specified by material and soot type
- Contents inventory with cleaning, storage and non-salvageable items identified
- Hazardous-material testing and any abatement, if applicable
- Repair-versus-replace decisions stated, not implied
- Who pulls permits and who schedules inspections
- Reconstruction scope kept distinct from restoration scope
- Allowances and exclusions written out plainly
- Payment milestones tied to completed work
- The change-order and supplement process
- Completion documentation and final walkthrough
If two estimates differ by a wide margin, the answer is almost always in the scope, not the labor rate. Read them side by side line by line before you look at the totals.
What Homeowners Insurance May Pay in Washington
The Washington Office of the Insurance Commissioner states that standard homeowners and property policies include protection against fire damage. What gets paid still depends on your limits, deductible, exclusions and endorsements, so treat what follows as a map, not an answer about your policy.
Dwelling, contents, other structures and loss of use
Most policies handle these as separate buckets with separate limits. The structure is one, personal property another, detached garages and fences another, and loss of use (also called additional living expenses) covers reasonable costs while the home is uninhabitable. Fire restoration touches all four, which is one reason a fire claim looks more complicated than any other claim you have filed.
Replacement cost versus actual cash value
Washington’s insurance regulator defines replacement cost as repairing or replacing covered property at current cost without subtracting depreciation, and actual cash value as that cost minus depreciation. On a replacement cost policy, the first check is often issued at actual cash value, with the recoverable depreciation released after the work is done and documented. Knowing which you have changes how you plan the money.
Ordinance or law coverage
When code requires more than a like-for-like repair, ordinance or law coverage is what may pay the difference. Many policies include a limited amount. Ask your adjuster in writing what yours provides before reconstruction is scoped.
Claim-handling timeframes
Under Washington regulation, an insurer generally must acknowledge an individual claim within 10 working days unless it pays first, and complete its investigation within 30 days unless it cannot reasonably do so. If the investigation is not finished within 45 days after proof of loss, the insurer must explain the delay in writing and update you every 30 days until it is. These govern the insurer’s handling, not how long your repairs will take.
Why the Insurance Estimate and the Contractor Estimate May Differ
This is the moment most homeowners start worrying they are being played, and usually nobody is. The two documents are written at different times, by people looking at different things.
An adjuster may measure a room from a doorway while a contractor measures every wall. Concealed damage behind drywall or under flooring often is not visible on the day the adjuster visits. Material identification differs: what is written as vinyl may be an engineered product with a different removal method. Asbestos survey results can arrive after the first estimate. Permit fees, code-required upgrades and contents work are frequently absent from an early structural estimate.
The fix is a supplement, which is additional documentation for covered damage or work that could not be confirmed the first time. A legitimate supplement identifies the location, quantities, photographs and cause. It is not automatically padding. If you and your insurer disagree on the value of the loss, your policy may include an appraisal process for resolving it. And if you choose an upgrade beyond what the policy covers, that difference should be shown on your estimate as your cost, in writing, before the work starts.
Washington Protections When Hiring a Fire Restoration Contractor
Verify registration, bond and insurance
Construction contractors in Washington must register with the Department of Labor & Industries. L&I’s Verify tool shows active registration, the surety bond, liability insurance, workers’ compensation status, citations and bond lawsuits. A general contractor carries a $30,000 bond and a specialty contractor $15,000, with liability coverage of either $250,000 combined single limit or $200,000 public liability plus $50,000 property damage. Registration is the floor, not proof of fire experience. Ask separately about fire-specific certification, documentation practices and reconstruction capability.
Bids, payments and paperwork
L&I advises getting three written bids and comparing scope, warranties, references and completion dates alongside price, and not paying in full before the job is finished. After a fire, treat emergency board-up and the reconstruction contract as two separate decisions. Securing the house may need to happen tonight; the rebuild contract can wait until you have compared scopes. Before signing an assignment of benefits, understand exactly what it transfers, since the Office of the Insurance Commissioner warns it can hand claim decisions to the contractor.
Cancellation rights and pressure tactics
Do not assume every home repair contract has a three-day cancellation window. The Washington Attorney General’s office notes that most signed contracts cannot simply be canceled unless a specific law applies, and while a three-business-day cooling-off period covers certain door-to-door and off-premises sales, the federal rule has an exception for emergency services. Ask for the cancellation terms in writing before you sign. And if someone shows up unsolicited at a fire scene pushing you to sign that day, that pressure is the warning, regardless of what they are offering.
Handyman, Unvetted Contractor, or Fire-Recovery Specialist
A skilled handyman can hang drywall. What a fire loss also requires is soot and odor assessment by surface type, moisture documentation that holds up with an adjuster, a defensible contents inventory, coordination of asbestos and lead requirements, permits and code-compliant reconstruction, and an estimate written in the format your insurer works from. Miss one of those and the gap becomes yours to pay, usually after the walls are closed. The practical advantage of a fire-recovery specialist is a single accountable party from the board-up through the final inspection, with one scope that does not get handed off halfway.
Getting an On-Site Fire Damage Assessment Near Renton
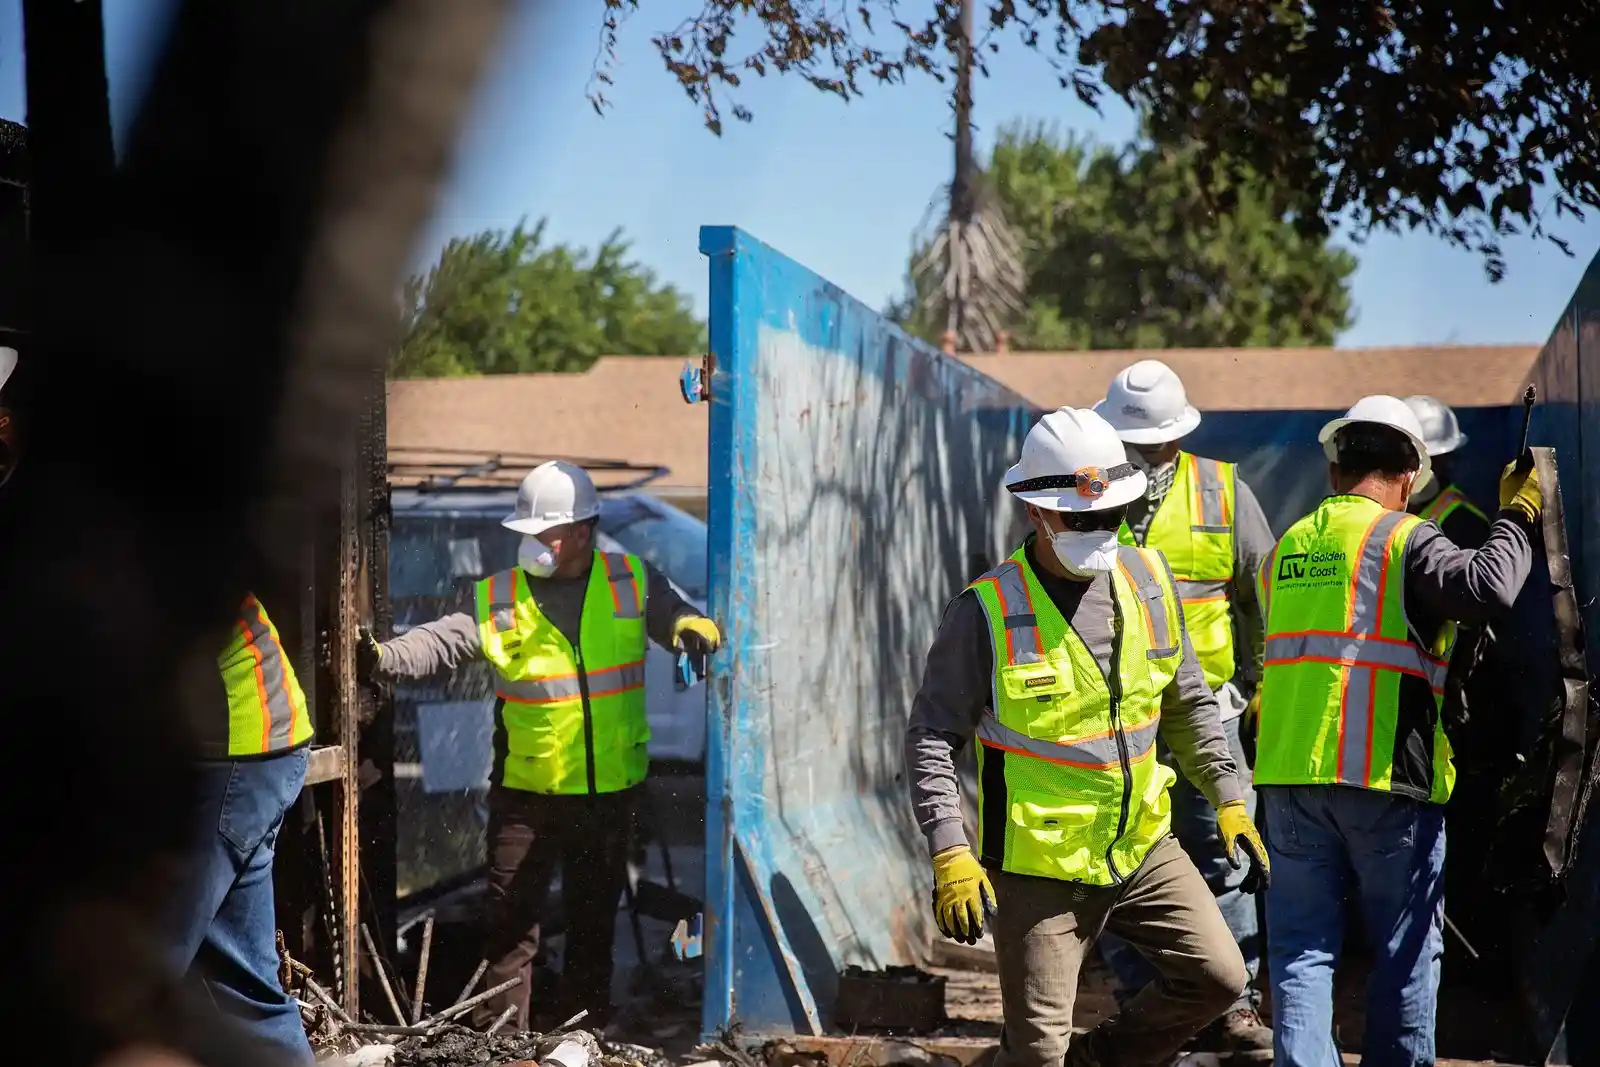
Golden Coast Construction & Restoration keeps a permanent office in Renton and answers emergency board-up calls 24/7. Our crews are IICRC-certified, our Washington contractor registration can be checked by name in L&I’s Verify tool, and we handle both sides of the work: fire and smoke restoration, and full reconstruction when the loss is structural. We write room-by-room scopes with photographs for your adjuster, arrange asbestos and lead testing where the work warrants it, run QA inspections at milestones, and bill against completed milestones rather than asking for the job up front.
What we will not do is quote your fire from photographs. Call for an on-site assessment, take the written scope, and compare it with others before you decide anything.
Does homeowners insurance cover fire damage restoration in Washington?
The Washington Office of the Insurance Commissioner states that standard homeowners and property policies include protection against fire damage. What is actually paid depends on your deductible, limits, valuation method and endorsements, so confirm the specifics with your adjuster and your policy documents.
Can I choose my own fire restoration contractor?
Yes. Once coverage is established, Washington homeowners select their own contractor. An insurer may suggest a provider, and you are not required to use it.
Why is my contractor’s estimate higher than the insurance estimate?
Usually because it includes something the first estimate could not: concealed damage, corrected measurements, hazardous-material requirements, permits, code items or contents. Ask for the difference documented line by line so it can be submitted as a supplement.
Can a contractor estimate fire damage from photographs?
Not reliably. Photos cannot show moisture in a wall cavity, charring depth in framing, or soot inside ductwork. A photo review can help decide how fast someone needs to get there. It is not an estimate.
Should I get three estimates after a house fire?
L&I recommends three written bids, compared on scope and warranty rather than the bottom line alone. Emergency stabilization is the exception: secure the house first, then take your time on the repair contract.