Key Takeaway
Insurance non-renewal after a wildfire is restricted in California: under Insurance Code section 675.1, insurers cannot refuse to renew a residential policy based solely on wildfire risk for one year after a Governor’s emergency declaration, if your home sits in a covered ZIP code. If your home was a total loss, additional protections require insurers to offer renewal for at least two annual periods or 24 months from the date of loss. Check the CDI moratorium bulletin for your exact ZIP code, request reinstatement in writing, and file a complaint with the California Department of Insurance if your insurer refuses.
If a wildfire has touched your area and your insurance company sent a non-renewal notice, here is the short version. In California, a homeowners insurance company generally cannot refuse to renew a residential policy because of wildfire risk alone for one year after a Governor’s emergency declaration for a wildfire, as long as your property sits in a ZIP code within or adjacent to the fire perimeter. That protection comes from California Insurance Code section 675.1. Check the California Department of Insurance moratorium list, ask your insurance company to rescind the notice if it applies, and file a Request for Assistance with the California Department of Insurance if they refuse.
If the moratorium doesn’t apply or has expired, start looking for replacement coverage right away while you gather your mitigation and repair records. This article is a calm California checklist for a homeowner who just got, or fears getting, one of these insurance non renewals, maybe while you’re still mid-claim or rebuilding. One thing to hold onto: your homeowners insurance situation and your property recovery are two separate problems. We’ll keep them straight.
Non-Renewal vs. Cancellation: Why the Difference Matters
These two words get used as if they mean the same thing. They don’t, and the difference decides what rights and deadlines you have.
Non-renewal means your insurance company honors your policy through the end of the current term, then declines to continue it. Your coverage doesn’t vanish overnight. When your home insurance is non renewed, you have until the expiration date, plus a required notice window, to line up something new.
Cancellation means the insurance company ends the policy mid-term, before the expiration date. California law limits this sharply. Once a covered residential policy has been in effect for 60 days (or immediately if it’s a renewal), an insurance company can only cancel for specific reasons: nonpayment of premium, fraud or material misrepresentation, certain criminal convictions, grossly negligent acts that substantially increase the hazard, or a physical change that makes the property uninsurable. Wildfire risk in your area is not on that list.
So if your notice says the word “cancel,” look closely at the reason. A mid-term cancellation for wildfire risk alone usually isn’t permitted, and if your insurance canceled the policy mid-term on that basis, it’s worth challenging. Insurance non renewals at term end follow a different set of rules, which we’ll walk through next. Knowing which one you’re holding tells you how much time you actually have.
Read the Notice: Reason, Date, and Deadlines
Before you do anything else, read the notice slowly. The deadlines written into California law exist to give you time, and the details on the page tell you how much you have.
Here’s what to check:
- What reason does it give? If it says something like “wildfire risk” or “location in a high risk area,” that matters for the moratorium check coming up.
- What is your policy expiration date? This is your real deadline.
- Was the notice sent on time? For a covered residential policy expiring on or after July 1, 2020, a non-renewal notice must be delivered or mailed at least 75 days before expiration. If the insurance company sends it late, your policy stays in effect for 75 days from the date the notice was mailed or delivered.
- Does it state a specific reason and how to reach the California Department of Insurance? A proper non-renewal notice must include the specific reason or reasons and Department of Insurance review information.
Insurance cancellations run on tighter clocks than non renewals. A residential cancellation notice generally must arrive at least 20 calendar days before the effective date, and at least 10 calendar days for nonpayment of premium or fraud. If the paperwork doesn’t match these rules, that’s worth raising with your insurance company and the California Department of Insurance.
What Counts as a Residential Property Policy Here
These rules apply to residential property insurance, which California defines to include individually owned residential structures of not more than four dwelling units, along with certain condominium and mobilehome policies, contents coverage, and renters contents policies. If you own a single-family home, a duplex, a triplex, or a fourplex, or you rent and carry contents coverage, these protections most likely reach your homeowner’s policy. Most standard homeowners insurance policies from major carriers fall within this definition.
Does a California Wildfire Moratorium Protect You from Insurance Non Renewal After a Wildfire?

The one-year moratorium is the strongest protection available to many homeowners after a fire, and it’s the first thing to check. Under California Insurance Code section 675.1, once the Governor declares a wildfire state of emergency, california insurance companies may not cancel or refuse to renew a residential policy based solely on the fact that the insured structure sits in an area where a wildfire occurred. That protection lasts one year from the governor’s emergency declaration, and it applies whether the loss came from a house fire or a declared wildfire emergency.
The catch is geography. The moratorium applies to ZIP codes within or adjacent to the fire perimeter, not to a whole city or county by name. The California Department of Insurance works with CAL FIRE and Cal OES to map each fire’s perimeter and identify the adjacent ZIP codes, then issues a bulletin listing exactly which ones are covered.
This is why guessing by your city name is a mistake. Two neighbors on the same street usually share a ZIP, but the line that matters is drawn by the fire perimeter and the official bulletin, not by what feels close. The only reliable answer is the actual list from the California Department of Insurance for your fire.
How to Check If Your ZIP Code Is Covered
This is a five-minute check, and it’s worth doing before you make any calls.
- Go to the CDI moratorium page and find the bulletin for the fire that affected you.
- Look for your exact ZIP code on the listed ZIP codes for that declaration.
- Note the start date of the one-year protection, so you know when it began and when it ends.
These bulletins change with every declared fire, and the California department issues new ones as emergencies are declared. This article reflects what was published as of its writing, so confirm the current bulletin list yourself before relying on any date. If a new fire and a fresh governor’s emergency declaration cover your area, a new one-year clock may start for those ZIP codes.
Pasadena and the Eaton Fire: A Careful Note on Timing
For Pasadena and the wider Los Angeles County area of Southern California, honesty matters more than reassurance here. The January 17, 2025 amended CDI bulletin for the Palisades, Eaton, and related fires listed many Pasadena-area ZIP codes under the moratorium, including Eaton Fire ZIPs like 91101, 91103, 91104, 91105, 91106, 91107, and 91108. That protection began January 7, 2025, which means its one-year window ran through January 7, 2026.
So if you’re reading this after that date, the basic one-year ZIP code moratorium from that specific bulletin has passed. Don’t assume it still shields you. That doesn’t leave you without options. If your home was a total loss or is still being rebuilt, separate protections may still apply, and a later governor’s emergency declaration for a newer fire could start a fresh moratorium in your ZIP code. A more recent event like the Hughes Fire in northern Los Angeles County is a reminder that Southern California sees new declarations regularly. If the Hughes Fire or another fire triggered a declaration covering your ZIP codes, a new one-year protection window may apply. Check the current CDI bulletin list, then read the next section.
If the Moratorium Applies: Ask for Reinstatement in Writing
If your ZIP code is on a current bulletin and your notice is based on wildfire risk, the moratorium is on your side. CDI’s guidance is to go back to the insurance company and ask them to fix it.
- Call your insurance company. Tell them your ZIP code is covered by the CDI moratorium for the declared fire, and ask them to rescind the notice and renew or reinstate your policy.
- Put it in writing. Follow the call with an email or letter that names the fire, the bulletin, your ZIP code, and the moratorium start date. Keep a copy. A written record protects you if there’s any dispute later.
- Escalate if they refuse. If the insurance company refuses to reinstate you, file a Request for Assistance with the California Department of Insurance. CDI reviews the complaint and can intervene when a company appears to be violating the moratorium.
You don’t need legal language to do this. Clear facts, dates, and a paper trail carry more weight than anything fancy.
If Your Home Was a Total Loss or Is Still Being Rebuilt
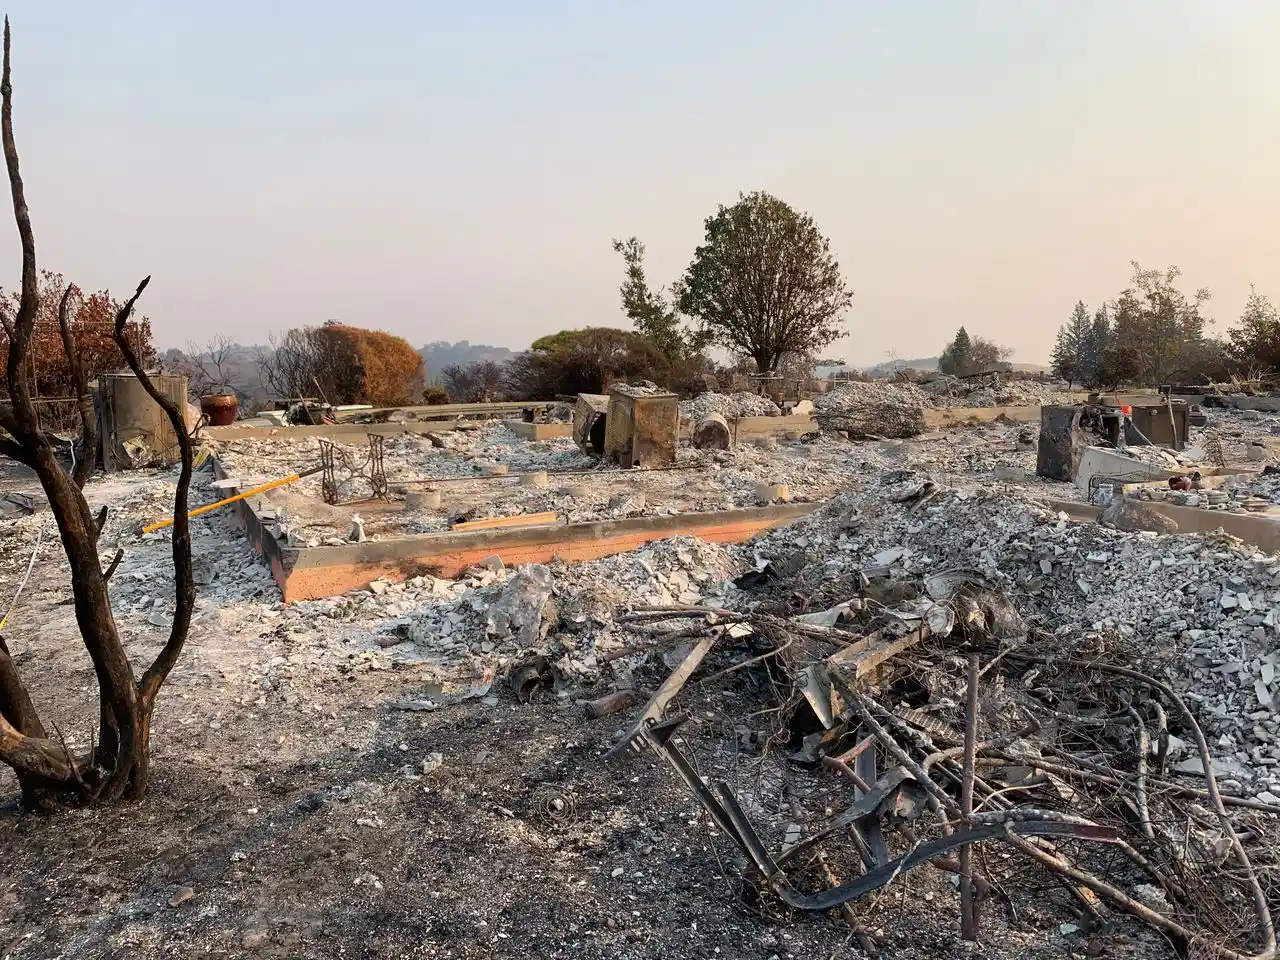
This is the piece most articles skip, and it’s the one that matters most if your house burned. California Insurance Code section 675.1 carries extra protections after a total loss to the primary insured structure, and they’re separate from the one-year ZIP moratorium.
If your reconstruction isn’t finished by your renewal date, your insurance company can’t simply walk away. It has to consult with you and adjust your limits and coverages, write an additional policy, or attach an endorsement that reflects the changed condition of the property while it’s being rebuilt. While the primary structure is under reconstruction after a total loss, the insurance company may not cancel except for the specified legal reasons, and it cannot use the damaged condition from that total loss as the sole basis for cancellation.
There’s more. If the total loss was caused by a disaster, wasn’t also due to your own negligence, and no unrelated change made the property uninsurable, the insurance company must offer renewal for at least the next two annual renewal periods, and no less than 24 months of coverage from the date of loss.
To use these protections, keep your records in order: your claim file and diary, permits, contractor estimates, and rebuild progress. A clear, dated record of where your reconstruction stands makes it far harder for anyone to claim your home is simply too risky to insure while the work is underway.
If the Moratorium Doesn’t Apply: How to Find Coverage Now
If no current moratorium covers your ZIP code and your home wasn’t a total loss under the rebuilding protections, don’t wait. Insurance non renewals in wildfire prone areas have become common, and there are real paths forward to find coverage.
Start with these steps:
- Ask your insurance provider a direct question. “What specific mitigation documentation would change this decision?” Sometimes proof of home hardening or defensible space can help you retain or restore coverage.
- Don’t wait for a complaint to resolve before you shop. Even if you’ve filed with the California Department of Insurance, keep looking for coverage in parallel. A gap in home insurance can create problems with your mortgage lender.
- Contact multiple agents and brokers. An independent agency can check several standard insurance carriers at once and lay out your coverage options in one conversation. The voluntary market still writes policies in many areas, especially for homes that have been hardened.
- Use CDI’s tools. The department of insurance offers a Home Insurance Finder and comparison resources to help you locate carriers writing homeowners insurance in your ZIP codes.
If the standard market turns you down, ask your insurance agent about surplus lines insurers. These specialty insurers, sometimes called surplus lines carriers, will cover risks that private insurers in the traditional market won’t, though the traditional coverage they offer can carry higher costs and less comprehensive coverage. The California FAIR Plan exists as a last resort option if you truly can’t find new coverage in the voluntary market. Before you lean on it, understand what it is and isn’t.
The California FAIR Plan Is a Last-Resort Option, Not a Full Policy

The FAIR Plan is there to make sure you can get basic fire insurance when no traditional insurer will write your home. That’s real, and for some homeowners with high wildfire risk properties it’s the difference between coverage and none. But it is narrower than a standard homeowners policy, and you should know the gaps before you rely on it.
FAIR Plan coverage is limited to losses from fire or lightning, internal explosion, and smoke. It generally does not cover liability, theft, or water damage. To fill those gaps and move closer to comprehensive coverage, CDI recommends pairing it with a separate Difference in Conditions (DIC) policy, which adds back many of the perils a standard homeowners policy would normally include.
So think of the FAIR Plan as one layer, not a finished roof. The combination of a FAIR Plan policy plus a DIC policy can approach the protection you had before, but it takes deliberate assembly. That pairing deserves its own deeper look, and we cover it separately in our guide to the FAIR Plan and DIC coverage after a wildfire non-renewal.
Market Context: Why California Insurance Companies Are Issuing More Non Renewals Due to Wildfire Risk
If it feels like insurance cancellations and non renewals are happening to everyone, you’re not imagining it. Increased wildfire risk across the state has pushed many major carriers to pull back from high risk areas, and homes that were once easy to insure now sit in ZIP codes that carriers treat as too exposed. For those companies it is partly a business strategy shaped by rising costs, and a property’s risk profile now drives the decision more than any single homeowner’s history. CDI’s Sustainable Insurance Strategy, updated in early 2026, counts 662 ZIP codes in distressed areas and lays out rules requiring insurance companies to write more policies in wildfire-distressed areas, with the goal of reversing FAIR Plan growth. The FAIR Plan itself reported roughly 696,562 dwelling and commercial policies in force as of mid-2026, a figure that keeps climbing as tens of thousands of high risk properties are non renewed and lose private coverage each year. The state is actively working on this. Your job right now is narrower: protect your own homeowners insurance and your own home.
What Documentation Helps After a Wildfire
Good documentation won’t reverse a non-renewal on its own. What it does is give your insurance company, broker, adjuster, and lender a clear, honest record of your home and your claim, which helps every one of those conversations go better.
Focus on gathering:
- Photos and video before cleanup. Document the damage before anything is moved, cleared, or repaired. This is your baseline.
- A claim diary. Log every call, name, date, and promise. Memory fades fast when you’re overwhelmed.
- A written mitigation and repair or rebuild scope. A clear description of what needs to be done, room by room and system by system, including your personal property inventory.
- At least one licensed contractor’s estimate or bid. CDI specifically notes that insurer estimates can contain errors or miss local post-disaster conditions, so an independent licensed estimate helps you compare against your coverage limits.
Actual Cash Value vs. Extended Replacement Cost: The Setting That Shapes Your Rebuild
One coverage detail decides how much you can actually rebuild. Actual cash value pays the depreciated value of what was lost, which is often less than what rebuilding costs today. That actual cash figure can fall well short of a modern rebuild. Extended replacement cost pays to rebuild, up to a stated percentage above your policy limit. Read your homeowner’s policy or ask your agent which one you have, because it shapes every rebuild decision. Confirming you carry adequate coverage now, before a loss, is far easier than discovering a shortfall mid-rebuild. For a fuller walkthrough, see our guide to documenting a wildfire insurance claim.
Create Defensible Space and Harden Your Home to Help Find or Keep Coverage
California’s Safer from Wildfires framework can earn you insurance discounts and gives you documented proof of a lower-risk home. CDI says every qualifying action earns a discount, and more actions can mean more savings. It won’t guarantee an insurance company reverses a decision, but it strengthens your case and, when you rebuild, it builds resilience into the structure itself. As more carriers recognize the value of hardening, that record becomes one of your better insurance options.
The framework works in three layers: the structure, the immediate surroundings, and the community. Ten qualifying actions include steps to create defensible space and harden the building:
- A Class-A fire-rated roof
- A 5-foot ember-resistant zone around the home
- Ember- and fire-resistant vents with 1/16 to 1/8 inch metal mesh
- 6 inches of non-combustible material at the base of exterior walls
- Upgraded windows
- Defensible space compliance
- Removing combustible sheds and outbuildings to at least 30 feet
- Recognized community wildfire programs
If you’re rebuilding, many of these can be designed in from the start, and installing fire resistant materials is one of the quiet advantages of reconstructing after a total loss rather than patching. Choosing fire-resistant materials for the roof, vents, and exterior walls is basic coverage of the highest-risk points on a home. For homes in wildfire prone and high risk areas, that hardening is also essential protection and the record you’ll show the next carrier when you go to find coverage.
Be Careful Who You Hire While Insurance Is Unsettled

After a fire, contractors will come to you, sometimes fast. Most are honest. A few count on you being overwhelmed. California law gives you specific protections, and using them filters out the bad actors.
- Verify the license. Check any contractor’s status and complaint history through the CSLB license lookup before you sign anything. Don’t rely on a business card or a third-party listing.
- Get it in writing. A California home improvement contract must include a detailed written payment schedule, the contractor’s identifying information and license number, who pulls the permits, and written change orders for any change in scope or price.
- Know the down-payment cap. By law, the down payment can’t exceed $1,000 or 10% of the contract price, whichever is less, not counting finance charges. Anyone demanding more up front is a warning sign.
- Tie payments to work. Progress payments can’t exceed the value of work actually performed, aside from that lawful down payment.
- Use your right to cancel. Most qualifying home improvement contracts carry a three-day right to cancel, and five days for homeowners 65 and older in certain transactions.
Watch for pressure tactics. “Sign by Friday to lock in this price” is not urgency you created, and a reputable contractor won’t manufacture it. A real firm gives you the contract, answers questions, and lets the cancellation window run.
How a Licensed Fire Restoration and Reconstruction Company Fits In
Let’s be clear about roles. Golden Coast Construction & Restoration is not an insurance company, an agent, or a lawyer. We can’t reinstate your policy or file your complaint. What we do is the property-recovery side of this, which is where honest documentation and code-compliant work protect you.
On the recovery side, that means emergency board-up and roof tarping, documenting smoke and soot damage, structural drying when fire suppression brings water into the picture, contents documentation, and a written repair or rebuild scope your adjuster can work from. When a fire is still an immediate threat, that emergency services work is what keeps a damaged home from getting worse while everything else is unsettled. It’s worth keeping two ideas separate: restoration means cleaning, drying, mitigating, and repairing, while rebuilding means reconstruction after major structural or total loss. They call for different scopes, and treating one like the other causes problems down the line.
We’re IICRC-certified, and our California work is licensed under CSLB #838443, which you can and should verify yourself through the CSLB before you hire anyone. We keep a permanent office in Pasadena and offer 24/7 emergency board-up, so a Los Angeles County homeowner isn’t left waiting after the fire is out. Our payment schedule follows the milestone rules above, with QA inspections at each stage and a signed certificate of completion at the end. The point isn’t to sell you. It’s to give you a clear record and by-the-book work while you sort out the insurance side.
Frequently Asked Questions