


Key Takeaway
Your homeowners insurance generally pays for board-up after a fire when the loss is covered: you authorize the work, the contractor secures exposed windows, doors, and the roof, and your insurer reimburses reasonable costs. Board-up counts toward your deductible, not as separate free money. Save every receipt, photograph the damage before and after, and get your claim number to your adjuster quickly.
If you’re standing outside a fire damaged home with broken windows and a hole in the roof, here’s the short answer: you, the property owner, usually arrange and authorize the board up, and your homeowners insurance generally reimburses reasonable board up costs when the fire is a covered loss. Save your receipts, take photos before and after, and keep the paperwork. One more thing worth knowing now, before anyone hands you a clipboard: don’t sign a full restoration or rebuild contract just to get your property secured. Emergency board up is a small, temporary job. It shouldn’t lock you into a large one.
Who Usually Pays for Emergency Board Up After a House Fire?
Someone has to authorize the work, and that someone is almost always you. After a house fire, the fire department secures the scene and leaves. It does not pay for private board up in most jurisdictions. A board up crew covers the exposed windows, damaged doors, and roof, then invoices the person who hired them. These crews usually expect to be paid quickly.
There are three common ways the money flows. You pay the contractor and your insurance company reimburses you. The contractor bills your insurer directly, if the contractor offers that. Or your insurer arranges its own vendor for these emergency services. Any of these can be fine. Board up costs typically count toward your deductible, so they aren’t separate free money. Ask your insurer which path they prefer before the work starts if you have time to make the call.
Does Homeowners Insurance Cover Board Up Services After a Fire?
Yes, most insurance policies cover it, with one important qualifier: insurers reimburse reasonable costs to protect the property after a covered fire loss. The California Department of Insurance tells homeowners to make temporary repairs to prevent further damage and to save the receipts, because the insurer will reimburse reasonable protection costs. Nationally, the Insurance Information Institute says most homeowners policies cover reasonable and necessary temporary repairs up to a specified amount.
Two things surprise people. First, temporary-repair payments are part of your total claim settlement, not extra money outside it. Second, if a crew charges well above local industry standards, the insurance adjuster may cover only part of the bill. “Temporary repair” just means work that holds the fire damage in place until proper repairs happen. Board up services qualify. A new roof does not.
Why Board Up Is Treated as a Temporary Repair, Not a Full Repair

Board up and roof tarping are protection, not restoration and not rebuilding. Their job is to keep the fire loss from getting worse while everything else gets sorted out. That’s why insurers treat them differently from cleanup or reconstruction.
The openings often aren’t only from the fire. FEMA’s After the Fire guide explains that firefighting efforts may break windows, cut roof openings, and open walls to vent smoke and confirm the fire is out. Once the fire department leaves, those entry points invite rain, wind, theft, animals, and anyone who wanders in. The California Department of Insurance warns that a policy may not cover later further damage if you didn’t take reasonable steps to secure the home. A professional board is how you take that step and prevent further loss to the structure and what’s inside it.
Should You Wait for the Adjuster Before Securing the Property?
No. Don’t leave exposed areas unprotected while you wait, as long as the fire department has released the home for safe access. Leaving the property unsecured invites the kind of secondary damage insurers expect you to prevent. FEMA advises not to re-enter a fire damaged property until the fire department says it’s safe, so don’t attempt anything yourself before that clearance.
Take photos or video of the fire damage first, if you can do it safely. Then call your insurer as soon as possible and ask how they want the board up handled. Securing the property now protects your claim. It does not hurt it. The one thing to hold off on is permanent repair. Don’t replace the roof or rebuild a wall before the adjuster has inspected, because they need to see the fire damage as it is.
Who Pays for Board Up in Different Situations?

| Situation | Who usually pays / handles it |
|---|---|
| Homeowner with insurance | You arrange the work; your insurer reimburses reasonable costs on a covered loss. |
| Homeowner without insurance | You pay directly. FEMA notes community groups, nonprofits, faith organizations, and public agencies may help. |
| Renter | The building owner usually handles structural board up. Your renters policy may cover belongings and temporary housing costs. Call your landlord and renters insurer right away. |
| Landlord / rental owner | The owner arranges board up; the property policy generally applies. |
| Condo / HOA | The association often handles the building envelope; your unit policy covers the interior. Check your CC&Rs. |
| Fire caused by a neighbor or third party | Start with your own insurer. Ask the adjuster about recovery from the other party rather than assuming it. |
| Mortgage lender involved | You still arrange the work; the lender may be named on claim payments and can be part of the settlement process. |
For a neighbor-caused fire, resist any promise that the other party’s insurance will simply pay. Your own insurer moves first, then pursues recovery if it applies. Most property owners never have to sort that out alone if they document things well from the start.
What to Save for Your Insurance Claims
Insurance documentation is what turns a board up bill into a reimbursed one. Insurance claims move faster when the paperwork is complete. Keep all of this:
- Photos or video of the fire damage before board up
- The fire department incident report number
- Your claim number
- Your adjuster’s name and contact
- A written scope of the board up work
- The signed work authorization
- A dated invoice and receipt
- Notes on how many openings, windows, and doors were secured and why
- Photos after board up
California guidance is clear on keeping records of expenses and communications with your insurer. Good insurance coordination makes all the difference here, because a dated invoice tied to photos and a claim number is hard to dispute.
Don’t Sign a Full Restoration or Rebuild Contract Just to Get Board Up Services
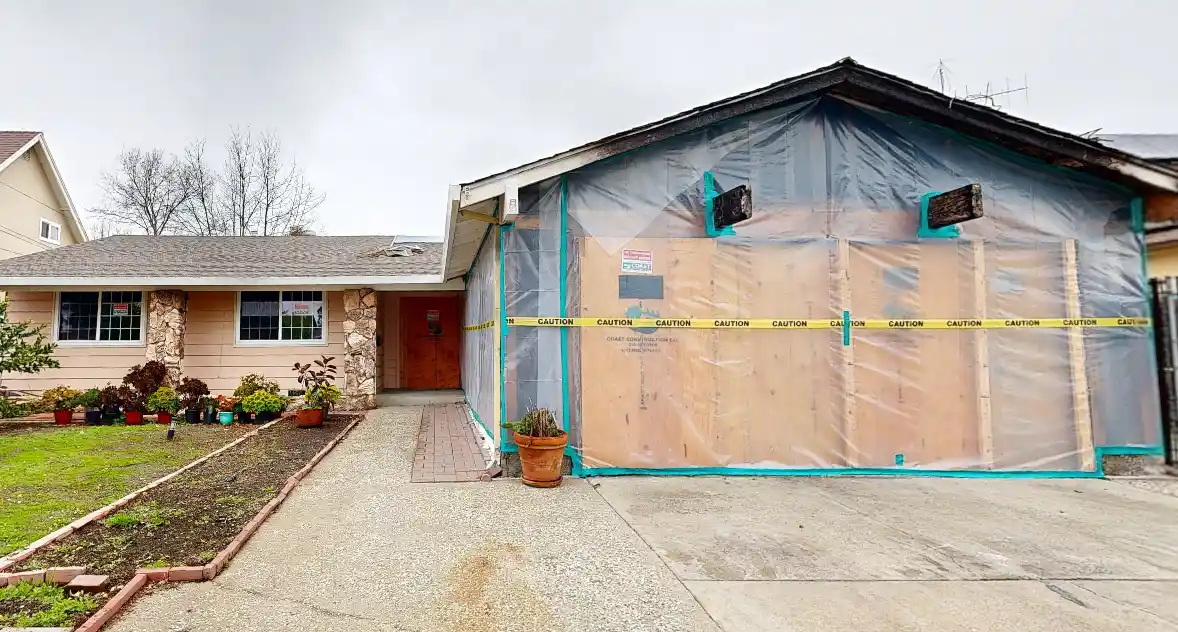
An emergency work authorization should cover board up and roof tarping only. Nothing more. Soot removal, smoke damage cleanup, contents work, drying, and reconstruction are separate scopes with separate decisions, and you shouldn’t commit to them under stress in a parking lot.
A few things that protect you, framed as what to watch for. Be wary of anyone pressuring you to sign right now or by a deadline. The disaster already created urgency; a good contractor won’t manufacture more. Don’t sign over your insurance checks. Don’t hand over large cash payments. Don’t let payments run ahead of completed work. And be careful with a broad assignment of benefits that signs away your control of the claim. A limited, written scope for the board up services keeps you in charge.
California Rules That Protect Pasadena Property Owners
If your property is in Pasadena or elsewhere in California, several rules work in your favor. Verify the contractor’s licensing and CSLB license before signing anything. A written contract is required for home improvement work over $500. The down payment cannot exceed $1,000 or 10% of the contract price, whichever is less. Progress payments cannot exceed the value of work already performed.
You also have cancellation rights: three business days on most qualifying contracts, five if you’re 65 or older, and seven business days for repair or restoration contracts on a home damaged by a sudden event in a declared emergency (California Business and Professions Code section 7159). Your insurer is on a clock too. California requires certain claim notices within 15 days, a decision to accept or deny within 40 days of proof of claim, and payment within 30 days of acceptance, with stated exceptions. For rebuild decisions, the City of Pasadena recommends getting at least three estimates. That’s for later. It’s never a reason to delay emergency board up.
Board Up Is Only the First Step in Fire Damage Restoration

Securing the home is the beginning of a sequence, not the whole job. This systematic approach to securing the property runs roughly like this:
- Fire department safety release
- Board up and roof tarping
- Claim setup and documentation
- Smoke, soot, and water-suppression drying, plus contents assessment
- Hazardous-materials (asbestos or lead) testing where warranted
- A restoration work plan
- Reconstruction, if there’s structural damage or total loss
The standing water left by firefighting matters here. The EPA recommends drying wet areas and items within 24 to 48 hours to help prevent mold growth, which is why suppression water gets addressed early, before restoration work begins in earnest. Professional fire and smoke work follows the ANSI/IICRC S700-2025 standard. Quality board up uses 3/4-inch exterior grade plywood over windows and doors, installed with proper installation techniques and heavy duty tarps over roof openings. When a fire touched multiple rooms, this recovery process protects both the structure and its contents. Restoration (cleaning and salvage) and reconstruction (rebuilding what’s lost) stay separate scopes with separate contracts.
How Long the Boards Stay and What Board Up Typically Costs
Most board up jobs on fire damaged homes take about two to six hours, depending on how many openings need securing and the roof situation. On larger fire damaged structures or commercial buildings, it can run longer. The boards stay in place for days or weeks depending on how quickly your claim and repairs move. Quality emergency board up services use 3/4-inch plywood measured to each opening precisely and fastened properly, not scrap tacked over broken windows or bought loose from a hardware store.
On price, an honest figure for your property takes an on-site look. Anyone quoting a firm number sight-unseen, before seeing your openings and access, should give you pause. That’s a red flag, not a convenience. A real assessment protects you and your claim.
When to Call for Emergency Services on Fire Damaged Homes

Call for immediate response when you have exposed openings, roof damage, smoke or soot moving through the walls, wet materials from suppression, or access that isn’t safe. Thin plastic sheeting or a loose board over a window won’t hold, and it leaves real safety hazards behind. A licensed restoration team securing your fire damaged property protects you better than a handyman or an unvetted crew because the work follows IICRC standards, the documentation is built for your adjuster, repairs are code-compliant, and payments follow milestones tied to completed work. This protective step guards against additional damage, further property damage, unauthorized entry, and the theft that follows when a home sits open. Fire damaged homes need that discipline more than most jobs, because the damage is often worse than it looks.
Golden Coast Construction & Restoration handles fire recovery from emergency board up through rebuild. We’re a California General Contractor (CSLB #838443, verifiable on the CSLB site), IICRC-certified, with a permanent local office serving Pasadena and Southern California and 24/7 emergency board up services. When our professionals arrive, we secure the openings, then work directly with adjusters and provide the insurance documentation your claim needs. Ask for a limited emergency scope and an on-site assessment first. No pressure, no rush you didn’t already have.


